Productivity and financial sovereignty are shields against a fragmented world order
With demographic decline and sluggish growth that fails to offset higher public debt, Europe must make hard choices.
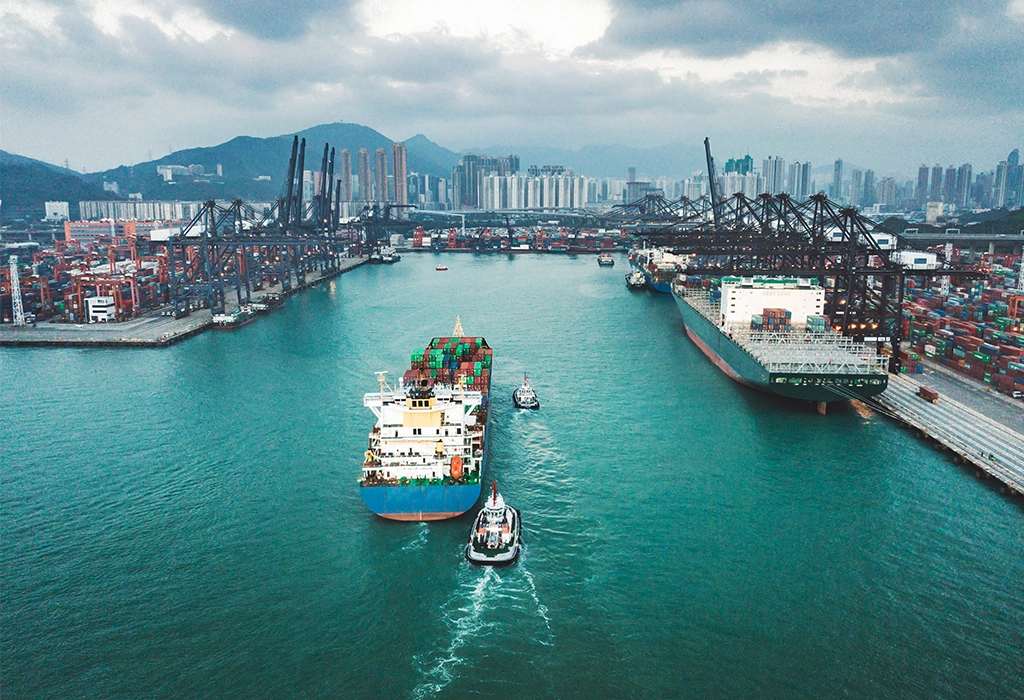
In the new world order, economic progress is measured not by GDP, but by financial sovereignty and productivity.
U.S. hegemony is eroding and has left an unstable geopolitical chessboard, where trade tensions and military rearmament put pressure on already struggling public finances. Global public debt, which hovered near 94% of GDP in 2025, is on track to be at 100% in 2029, the International Monetary Fund forecasts.
If economies are not to drown in debt, they must grow faster than their financing costs.
But how is this to be achieved, when there are fewer working-age people than before, meaning economies risk losing momentum precisely when they most need it to fund pensions and healthcare?
For Nuria Mas, a first, necessary step lies in enlarging our chances to live longer and healthier lives. Staying active, whether by working, volunteering or caring for others, can contribute to physical and mental well-being and help prevent chronic illness.
Making this a reality requires changes in both organizations and healthcare. Companies will need to offer employment adapted to different life stages and facilitate continuous learning programs so employees can update skills and reshape career paths. Healthcare, meanwhile, will need to evolve toward a model that prioritizes prevention and management of chronic conditions, providing integrated care close to the community.
Mas and Pedro Videla gave a joint session on IESE’s Barcelona campus, in which they painted boosting productivity as an essential goal, not just for competitiveness, but as the only way to sustain the welfare state.
Not all economies share the same foundation for meeting these challenges, and Mas and Videla covered diverging situations in the United States, Europe and China.
The dollar shield in the United States
In the U.S., a still-dynamic economy meets with increasingly high needs. There, the IMF forecasts public debt will rise from 125.8% of GDP in 2026 to 142.1% of GDP by 2031.
Mas suggests that, within this context, an interesting asset to keep in mind is stablecoins. Since the 2025 GENIUS Act, these digital assets require full reserve backing with liquid assets like U.S. dollars or short-term U.S. Treasury bonds. This has stimulated market demand for these bonds and reinforces dollar dominance.
The U.S. has another strength, Videla says: its capacity to maintain investment dynamism. Business fixed investment grew at an annual rate of 11% in the first quarter of 2026. The Federal Reserve attributes much of that to the building of infrastructure needed for AI, from data centers to hardware and software.
However, inflation in the U.S. remains above the Fed’s 2% target, driven in part by tariffs and rising energy costs from the war with Iran.
Europe: Between the Strait of Hormuz and a hard place
In the eurozone, the situation in the Strait of Hormuz translates into upward pressure on prices, impacting economic growth. The European Central Bank projects average inflation of 3% in 2026 due to higher energy costs, while economic growth is expected to advance by a modest 0.9%. Frankfurt, which already raised rates in June and September, must decide whether to tighten further — risking slowing the economy and accepting price rises to avoid choking off growth.
Might this global fragmentation reignite international ambitions for the euro? The IMF reports that Europe’s single currency accounted for 20% of reported foreign exchange reserves in the first quarter of 2026, compared with 57% for the dollar. A reserve currency’s appeal is tied to the size of its economy, trust in its institutions and access to its financial system. U.S. sanctions have caused some central banks and investors to diversify their reserves.
Mas believes the general state of discontent could be a window of opportunity for Europe, though taking advantage of it requires more than merely capitalizing on others’ mistakes. The eurozone must urgently construct a unified capital market and issue euro-dominated safe assets that will be attractive enough to entice global capital.
China’s overcapacity trap
China continues to suffer from structural problems, growing far below its potential, burdened by a premature demographic winter, lingering aftershocks from the real estate collapse and depressed domestic consumption. Chinese households, cautious about the future, prefer saving to spending.
Meanwhile, Beijing persists in subsidizing production to sustain employment, exporting the surplus to the rest of the world. The risk here, Videla warns, is that China’s advancements remain incremental — optimizing existing technologies — rather than disruptive leaps capable of creating new markets.
China has proven that it knows how to manufacture more, better and cheaper. The question for the coming decade is whether it will convert its manufacturing dominance in tech leadership before the rest of the world stops buying its surpluses.